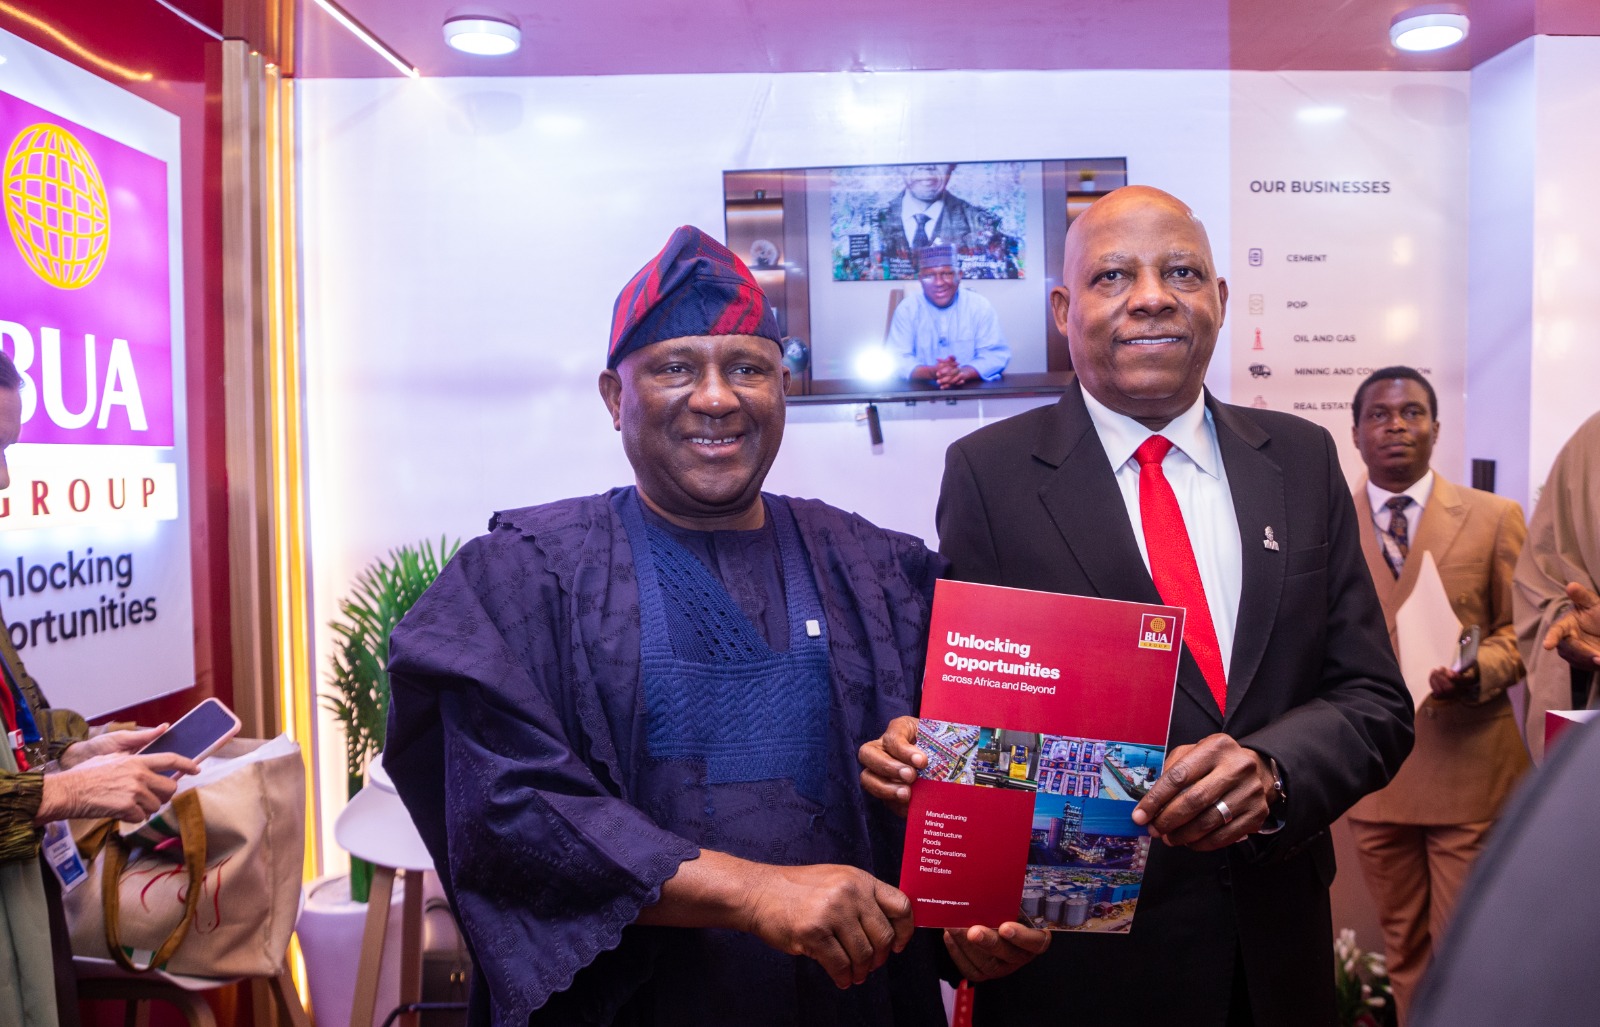
The Chairman of BUA Group, Abdul Samad Rabiu, has said President Bola Tinubu’s economic reforms are improving investor confidence, urging Nigeria to create at least 100 more indigenous industrial giants to accelerate production, job creation and economic growth.
Rabiu spoke on Monday at the 32nd Nigerian Economic Summit in Abuja, where he commended the administration’s foreign exchange, fiscal and tax reforms, removal of petrol subsidies and efforts to strengthen the banking sector.
He said improved access to foreign exchange had made it easier for businesses to plan investments, particularly manufacturers that depend on imported machinery and raw materials.
“Legitimate businesses can now access foreign exchange through the market at prevailing exchange rates, rather than depending on direct allocations from the Central Bank,” he said.
The BUA chairman, however, stressed that the gains from the reforms must translate into increased industrial production and better living standards for Nigerians.
“We must move from reform to results, from stabilisation to expansion, and from economic adjustment to shared prosperity,” he said.
Rabiu disclosed that BUA Foods and BUA Cement, both listed on the Nigerian Exchange, had a combined market capitalisation of more than $17bn, with BUA Foods valued at over $10bn and BUA Cement at about $7bn.
He said the group was investing in flour milling, pasta, noodles, edible oils, rice milling and feed mills, with projects scheduled for completion in 2027 expected to double production capacity across key food manufacturing operations.
According to him, the investments would strengthen food security, create jobs and support farmers and suppliers while expanding Nigeria’s capacity to serve markets across Africa.
“Our ambition is not simply to become bigger. It is to make Nigeria stronger,” he said.
Rabiu challenged the government and private sector to create an environment that would support the emergence of at least 100 more major Nigerian-owned businesses capable of investing in manufacturing, agriculture, mining, technology and other productive sectors.
“But the question we must ask ourselves is not simply how BUA can continue to grow. It is how Nigeria can create another one hundred BUAs,” he said.
He identified access to affordable, long-term financing as a major constraint to industrial development, noting that large manufacturing projects often require 10 to 20 years to realise their full potential.
He called for greater mobilisation of funds from commercial banks, pension funds, insurance companies, development finance institutions and capital markets to support productive investments.
Rabiu also urged the government to sustain policy stability and invest in infrastructure, arguing that these were essential to attracting capital and expanding local industries.
Citing the cement industry as an example, he said Nigeria had moved from importing almost 80 per cent of its domestic cement consumption to achieving self-sufficiency and becoming a net exporter.
He said similar progress could be achieved in other sectors through sustained investment in local manufacturing and agricultural processing.
Rabiu cited BUA’s integrated sugar project in Lafiagi, Kwara State, as an example of the opportunities available in agro-processing and value addition.
“Nigeria must not remain simply a supplier of raw materials or a market for finished products. We must become a nation that processes, manufactures and exports,” he said.
He also called for a new economic partnership among government, businesses and citizens, anchored on policy stability, productive investment, human capital development, long-term financing and shared prosperity.
On regional trade, Rabiu urged Nigerian businesses to take advantage of opportunities under the African Continental Free Trade Area, saying the country’s industrial future depended partly on expanding into regional and international markets.
The 32nd Nigerian Economic Summit, organised by the Nigerian Economic Summit Group, brought together Vice President Kashim Shettima, government officials, state governors, business leaders and policymakers to discuss strategies for accelerating economic growth and productivity.

- ‘Campaign slush fund’, Atiku alleges over Tinubu’s $20.5bn loan - October 27, 2026
- Court sacks NDC candidate, declares Mighty Man winner of Edo primary - October 27, 2026
- BUA chairman backs Tinubu’s reforms, seeks 100 more industrial giants - October 27, 2026